Commercial Auto Insurance: What It Covers, What It Costs, and Who Needs It
Learn when a business may need commercial auto insurance, how common coverages work, which factors influence cost, and what to compare before choosing a policy.
A construction company owner uses a pickup to collect materials before heading to a job site. A bakery sends an employee out in a van to make deliveries. A photographer regularly drives equipment to client locations.
All three vehicles may look ordinary, but the way they are being used creates a different insurance question from everyday personal driving.
That is where commercial auto insurance comes in.
Commercial auto insurance is designed for vehicles used in connection with a business. Depending on the policy and the business, it can address liability to other people, damage to company vehicles, medical-related coverages, uninsured or underinsured motorists, and certain situations involving rented or employee-owned vehicles.
The difficult part is not simply deciding whether a vehicle is "for work." Personal auto policies can allow some forms of business use, while other activities may fall outside their terms. Coverage also varies by insurer, state, vehicle type, and business activity.
Understanding those differences is more useful than assuming every work-related trip automatically requires the same type of policy.
What Is Commercial Auto Insurance?
Commercial auto insurance, sometimes called business auto insurance or commercial vehicle insurance, is coverage designed for vehicles used in business operations.
It can apply to a wide range of situations, including:
- a contractor's work van
- company-owned sedans
- delivery vehicles
- service trucks
- vehicles carrying tools or equipment
- fleets operated by a larger business
Commercial policies can also be structured to address certain vehicles the business does not own, depending on the coverage purchased.
The basic coverages may resemble those found in personal auto insurance, but the policy is written around business-related use and the risks associated with that use.
A small company with one vehicle may have very different insurance needs from a delivery operation running 20 vans, even though both fall under the broad commercial-auto category.
Why Personal Auto Coverage May Not Be Enough
One of the biggest mistakes a business owner can make is assuming that any trip made in a personally insured vehicle remains covered simply because the vehicle itself is insured. According to the National Association of Insurance Commissioners, personal auto policies often have limitations regarding business use.
The reality is more nuanced.
Some personal auto policies can accommodate limited business use. Others restrict or exclude particular commercial activities, especially when a vehicle is primarily used for business, owned by a company, used for deliveries, or used to transport people or goods for compensation. For additional business vehicle insurance guidance, business owners should review their exact usage with their agents.
That means the important question is not simply:
"Do I have auto insurance?"
It is:
"Does my policy cover the way this vehicle is actually being used?"
For example, occasional travel to a meeting may be treated very differently from using the same vehicle throughout the day for deliveries or transporting work equipment.
If a business-owned vehicle or a regularly used work vehicle is being insured only through a personal policy, the coverage should be reviewed carefully with the insurer.
Never assume that adding "business use" to a personal policy automatically provides the same protection as a commercial auto policy.
Who May Need Commercial Auto Insurance?
Ownership is one clue, but actual vehicle use is usually more important.
A business should consider reviewing commercial auto coverage when one or more of the following situations applies.
The vehicle is owned by the business
If a car, van, pickup, or truck is titled or registered to a company rather than an individual, a commercial policy is generally the appropriate place to start.
A personal policy is designed around personal ownership and personal use.
Driving is a regular part of the business
A business that routinely sends employees to job sites, customer locations, appointments, service calls, or delivery stops has a different exposure from someone who occasionally drives to an office.
The more central driving is to the business, the more important it becomes to make sure the policy reflects that activity.
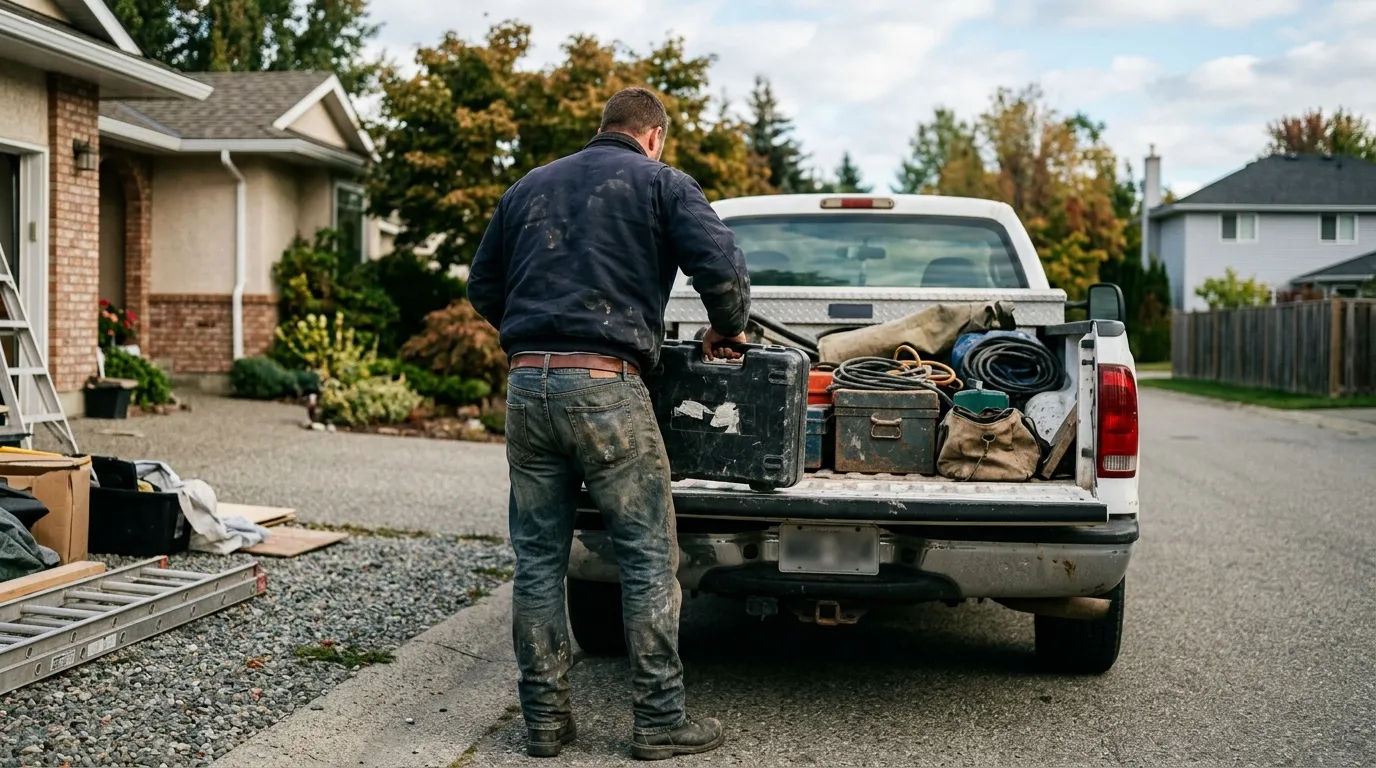
The vehicle carries equipment, inventory, or goods
Contractors, repair businesses, caterers, retailers, delivery businesses, landscapers, and many other companies use vehicles to transport items connected to their work.
The vehicle itself may need commercial auto coverage even though tools or cargo inside it may require separate insurance.
Commercial auto insurance should not automatically be assumed to insure every item carried in the vehicle.
Employees drive company vehicles
Once employees regularly drive vehicles owned or leased by a business, the company has a direct vehicle-related liability exposure.
The insurer will usually want information about who drives the vehicles and how they are used.
Employees use personal vehicles for company business
This situation is easy to overlook.
Suppose an employee uses a personal car to visit a client, make a bank deposit, collect supplies, or complete another work errand.
The employee's own auto policy may respond first depending on the circumstances, but the business can still face liability arising from the employee's work-related driving.
This is one reason businesses may consider hired and non-owned auto coverage.
A contract requires commercial auto liability coverage
Some clients, property owners, lenders, or contracting organizations require evidence of commercial auto insurance before allowing work to begin.
The required limit may be higher than the minimum amount needed merely to operate the vehicle legally.
Contract requirements should therefore be reviewed separately from state minimum insurance rules.
What About Rideshare and Delivery Work?
Rideshare and app-based delivery create another set of insurance questions.
Coverage can change depending on whether a driver is:
- using the vehicle personally
- logged into an app and waiting for a request
- traveling to a pickup
- actively transporting a passenger or delivery
A personal policy may not provide the same protection while the vehicle is being used to earn money, while coverage offered by a platform can also vary by phase, state, and company terms. The NAIC guidance on commercial ride-sharing explores these gaps in detail.
Drivers should not assume that either the personal policy or the platform automatically covers every stage.
Depending on the insurer and location, the solution might involve a rideshare endorsement, another form of business-use coverage, or a commercial policy.
Because platform insurance terms can change, drivers should verify current details directly with both their insurer and the platform before relying on the coverage.
What Does Commercial Auto Insurance Cover?
There is no single commercial auto package that every business buys.
A policy is normally assembled from several coverages according to the vehicles, business activity, applicable rules, financing requirements, and the amount of risk the company wants to retain.
Commercial auto liability
Liability coverage addresses bodily injury or property damage for which the insured business or driver becomes legally responsible after a covered auto accident.
It generally does not pay to repair the business's own vehicle.
Businesses must comply with the financial-responsibility and auto-insurance requirements that apply where their vehicles are registered and operated. Requirements vary by state and may also differ for certain commercial vehicles.
Contractual requirements can demand higher liability limits than the legal minimum.
Collision coverage
Collision coverage can help pay for covered damage to an insured business vehicle resulting from a collision with another vehicle or object, subject to the policy terms and deductible.
A business that owns an older vehicle outright may evaluate this coverage differently from one financing a newer, expensive vehicle.
Comprehensive coverage
Comprehensive coverage, sometimes described as other-than-collision coverage, addresses certain losses that do not result from a collision.
Depending on the policy, examples may include:
- theft
- vandalism
- fire
- falling objects
- certain weather-related damage
The exact covered causes of loss should always be confirmed from the policy.
Medical payments or personal injury protection
Medical Payments coverage and Personal Injury Protection can address certain medical expenses after an accident.
Whether these coverages are available, optional, or required depends heavily on the state and policy.
Do not assume the same rules apply nationwide.
Uninsured and underinsured motorist coverage
Uninsured and underinsured motorist coverage may provide protection when another driver is responsible for an accident but has no insurance or insufficient insurance for the covered loss.
Requirements and available forms of this coverage vary by state.
Hired and non-owned auto coverage
Hired and non-owned auto coverage can be particularly relevant to businesses that sometimes use vehicles they do not own.
"Hired auto" generally refers to vehicles the business rents, hires, leases, or borrows under circumstances covered by the policy.
"Non-owned auto" generally refers to vehicles used for business that are not owned by the business, such as an employee's personal car.
This coverage is primarily about the business's liability exposure. It should not be assumed to automatically cover physical damage to an employee's own vehicle or every type of rented vehicle.
The exact policy wording matters.
| Coverage | What It May Address |
|---|---|
| Commercial auto liability | Covered bodily injury or property damage the insured business or driver causes to others |
| Collision | Covered damage to an insured business vehicle caused by a collision |
| Comprehensive | Certain non-collision losses such as theft, vandalism, fire, or weather-related damage |
| Medical Payments / PIP | Certain medical expenses, subject to state rules and policy terms |
| Uninsured / Underinsured Motorist | Certain losses involving an at-fault driver with no insurance or insufficient insurance |
| Hired and Non-Owned Auto | Certain business liability arising from rented, borrowed, or employee-owned vehicles used for work |
How Commercial Auto Policies Can Be Structured
The appropriate policy structure depends on how the company uses vehicles.
One or a few business vehicles
A sole proprietor or small company may insure one van, pickup, or car used primarily for business.
The policy can then be built around that vehicle, its drivers, the territory in which it operates, and the coverage limits selected.
A fleet
Companies operating several vehicles can insure them through a commercial fleet arrangement.
The definition of a fleet and the way insurers price and administer it can vary.
Avoid presenting one universal vehicle-count threshold for what qualifies as a fleet.
Hired and non-owned exposures
A company may own no vehicles at all and still have an auto-related liability exposure.
If employees use personal cars for company errands or the business regularly rents vehicles, hired and non-owned coverage may deserve attention even without a traditional company fleet.
What Affects Commercial Auto Insurance Cost?
There is no reliable single "average" premium that applies to every business.
An insurer considers the characteristics of the business, vehicle, drivers, coverage, and usage before setting a price.
Common cost factors include the following.
Vehicle type and value
A small sedan, cargo van, heavy pickup, specialized truck, and passenger vehicle can present very different repair and liability risks.
More expensive vehicles can also cost more to repair or replace.
What the vehicle actually does
A van traveling short distances to local service appointments does not create the same exposure as a vehicle operating long routes every day.
Delivery work, passenger transport, towing, and specialized commercial operations can each affect pricing differently.
Mileage and operating area
Greater mileage means more time on the road and more opportunities for an accident.
The geographic area in which a vehicle operates can also affect risk because traffic conditions, theft levels, repair costs, and claim patterns differ between locations.
Driver records
The driving history of employees authorized to operate company vehicles can affect commercial auto insurance cost.
Recent accidents, traffic violations, and other driving-history factors may influence underwriting and pricing.
Number of vehicles and drivers
A company with one driver and one vehicle has a different exposure from a company managing many vehicles and employees.
Insurers may need updated driver and vehicle information as the business changes.
Coverage limits and deductibles
Higher liability limits generally provide more protection but can increase the premium.
For physical damage coverage, choosing a higher deductible may reduce the premium, but it also means the business accepts a larger out-of-pocket cost when a covered loss occurs.
Claims history
A business's previous auto claims can affect how an insurer evaluates future risk.
One claim does not create the same result with every insurer, and underwriting practices vary.
Industry and vehicle activity
A company carrying passengers, operating heavier vehicles, making frequent deliveries, or performing higher-risk driving activities can be evaluated differently from a business using a car for occasional local appointments.
That is why comparing commercial auto insurance cost based only on vehicle make and model can be misleading.
Two companies with similar vans can receive very different quotes because their drivers, routes, limits, claims history, and daily use are different.
How to Compare Commercial Auto Insurance Policies
Price matters, but it is only one part of the comparison.
A cheaper policy can become expensive if it leaves out a coverage the business actually needs.
Start by documenting how every vehicle is used
Before asking for quotes, list:
- every business-owned or leased vehicle
- regular drivers
- typical mileage
- usual operating area
- business purpose
- equipment or goods carried
- whether employees use personal vehicles for work
- whether the business rents vehicles
Accurate information helps an insurer evaluate the real exposure.
Separate legal minimums from business needs
The minimum required by law is not automatically the amount of coverage a company should buy.
A business may have:
- contractual insurance requirements
- lender requirements
- lease requirements
- significant assets to protect
- greater liability exposure than the statutory minimum addresses
Compare these requirements before choosing limits.
Review physical damage coverage vehicle by vehicle
Collision and comprehensive coverage may be more important for a financed or high-value vehicle than for an older vehicle with relatively little market value.
Compare the vehicle's value, deductible, premium, and the amount the business could comfortably absorb if the vehicle were damaged or lost.
Look closely at who and what is covered
Ask how the policy treats:
- employees
- occasional drivers
- rented vehicles
- employee-owned vehicles used for work
- newly acquired vehicles
- temporary substitute vehicles
- trailers or attached equipment
Do not assume a vehicle or driver is automatically covered merely because the company has a commercial auto policy.
Compare limits and deductibles, not just premium
Two quotes that look similar can provide substantially different protection.
Compare:
- liability limits
- physical-damage deductibles
- optional coverages
- endorsements
- exclusions
- driver restrictions
- territory limitations
A lower premium is meaningful only when the policies being compared address roughly the same risks.
Coverage Gaps Businesses Commonly Miss
Commercial auto problems often come from assumptions rather than a complete absence of insurance.
Assuming all business use is covered by a personal policy
Some personal policies permit limited forms of business use, while others restrict particular activities.
The solution is to disclose the actual use to the insurer rather than guessing.
Forgetting employee-owned vehicles
A company can still face liability even when it does not own the vehicle involved.
If employees regularly drive their own cars for company business, review whether hired and non-owned auto coverage is appropriate.
Failing to update drivers and vehicles
Insurance needs can change quickly when a business hires a driver, acquires another vehicle, expands its delivery territory, or begins a new type of work.
Policy information should reflect current operations.
Assuming commercial auto covers everything inside the vehicle
Commercial auto insurance primarily addresses vehicle-related risks.
Tools, merchandise, equipment, or other property carried inside the vehicle can be subject to separate coverage rules or policies.
Do not assume the contents of a work vehicle are automatically insured simply because the vehicle itself has comprehensive coverage.
Buying only on price
Premium is easy to compare. Policy wording is not.
A meaningful comparison should also consider coverage limits, exclusions, deductibles, endorsements, claims service, and whether the insurer is comfortable with the actual business activity.
Before Requesting Quotes, Gather This Information
A business can make the quoting process easier by preparing the information an insurer is likely to request.
Have available:
- business name and type of operation
- vehicle year, make, model, and identification information
- how each vehicle is used
- estimated annual mileage
- operating radius or territory
- regular drivers
- driver history information when requested
- current insurance information
- desired liability limits
- physical damage coverage needs
- information about rented or employee-owned vehicles used for work
The objective is not simply to find the lowest commercial auto insurance premium.
It is to make sure the policy reflects the vehicles, drivers, and business activities that actually exist.
A business that accurately describes how its vehicles are used is in a much better position to compare quotes meaningfully and identify coverage gaps before an accident exposes them.
Published by FinanzVault Editorial Team
FinanzVault provides independent, educational finance guides and transparent calculation tools. Our content is thoroughly researched, fact-checked against official financial data sources, and designed to help you make informed decisions.
Related Financial Guides
Truck Accident Liability: Who May Be Responsible and How Insurance Claims Are Affected
Learn how responsibility may be investigated after a commercial truck accident, which parties can become relevant, and how fault and evidence can affect an insurance claim.